Once you are under contract, the appraisal can feel like a number everyone is waiting on. You and the seller agreed on a price. Why does someone else need to weigh in?
Because an agreed price and an independent opinion of value are different things. If you are financing your purchase, your lender needs to evaluate the property as well as your ability to repay the loan.
Here is how I explain this step to Missouri buyers, without turning it into a lesson in mortgage vocabulary.
What is a home appraisal?
An appraisal is a professional opinion of a property’s value for a particular purpose and effective date. It considers the home’s characteristics and relevant market information. Missouri’s Real Estate Appraisers Commission regulates real estate appraisers in the state.
The lender generally arranges a mortgage appraisal. You may pay the appraisal fee, but that does not mean you select the value or direct the appraiser’s conclusion.
Not every loan requires the same valuation process. Fannie Mae describes value acceptance for some eligible transactions. Your lender can explain whether a traditional appraisal or another approved method applies to your loan.
What information does an appraiser consider?
Property size, condition, location, features, and comparable sales can all contribute to the analysis. The important word is comparable. A home down the street is not automatically a useful match simply because it is close by.
Think about two houses with the same bedroom count. One has substantially more finished space; the other has acreage and a detached shop. A quick price-per-square-foot calculation cannot settle every difference.
That is especially useful to remember when comparing a subdivision home in Grain Valley with a property outside Lone Jack or in rural Johnson County. Questions about land, improvements, and the available sales evidence deserve attention rather than an assumption that one nearby sale answers everything.
Fannie Mae’s consumer appraisal guide explains the factors appraisers consider and how the result fits into financing.
An appraisal is different from a CMA
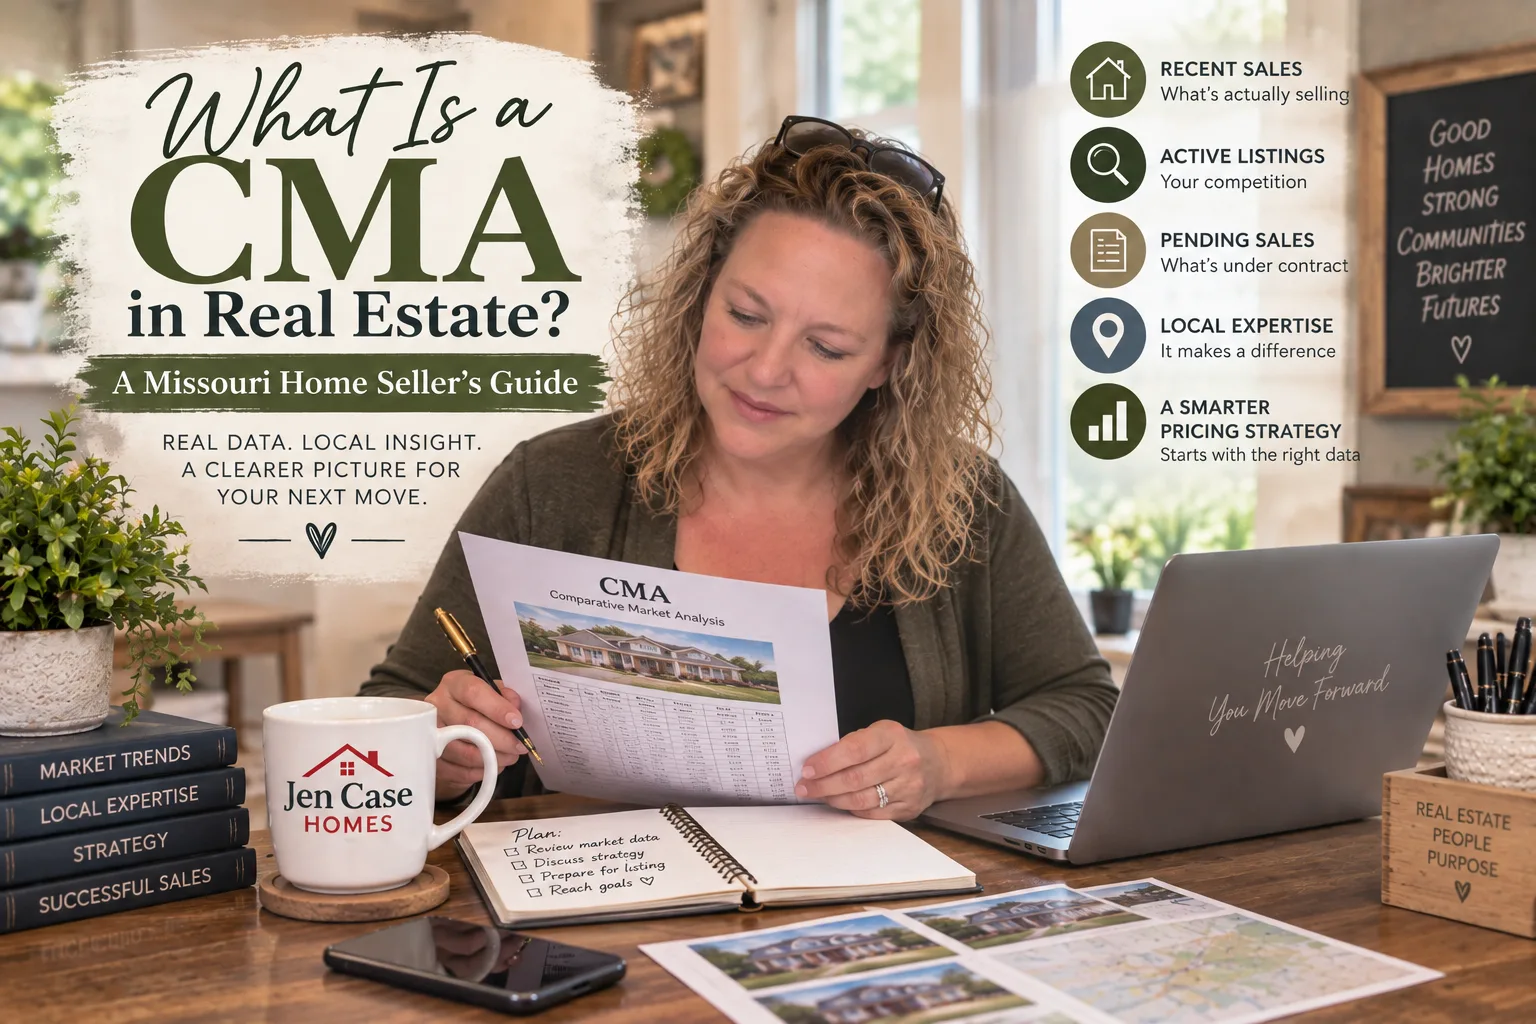
A comparative market analysis, or CMA, is a tool I use to discuss a property’s market position and a pricing strategy. A mortgage appraisal is a separate assignment with its own requirements and intended use.
It is possible for those analyses to reach different conclusions. Different dates, information, or comparable properties can affect the result. Neither my pricing recommendation nor the seller’s asking price instructs the appraiser what to report.
For the pricing side of the conversation, read What Is a CMA in Real Estate?.
What happens between ordering and receiving the report?
Ask your lender when the valuation will be ordered, what it will cost, and when the report is expected. If a property visit is needed, access has to be coordinated. The visit is only one part of the assignment; analysis and report preparation also take time.
For the rest of your purchase budget, my Missouri closing-cost guide helps you organize the expenses to discuss with your lender.
Rather than promising a fixed number of days, I want us to keep the expected delivery date beside the financing and closing deadlines. If there is a delay, we can ask the lender what remains outstanding and whether our timeline needs attention.
For a typical first-lien home loan, borrowers generally receive a copy of the appraisal or other written valuation. The CFPB’s appraisal-copy rule explains the timing and applicable exceptions. Ask your lender when and how you will receive yours.
Read more than the final number
When the report arrives, check the property description and ask about anything you do not understand. Are there apparent factual errors? Is the value subject to repairs or another condition? Has the lender accepted the report, or is a review still underway?
Send concerns through the lender’s process. Appraisal independence matters: asking for an error to be reviewed is different from pressuring someone to reach the contract price. Federal valuation-independence rules prohibit improper influence on a valuation.
What does the result mean for closing?
If the value supports the purchase price, that may clear one financing question. It is not a final loan approval. Other underwriting conditions may remain.
If the value is lower, pause and ask the lender to explain the effect on your loan amount and cash needed. Then review the purchase contract with your agent before deciding how to respond. A low number is something to investigate, not an instruction to make an immediate financial commitment.
And a satisfactory appraisal does not replace a condition review. My inspection-versus-appraisal comparison explains how the two fit together.
Keep the right people involved
The appraiser develops the value opinion. The lender explains the financing. I help you connect those answers to the transaction, keep track of deadlines, and work through the real estate decisions in front of you.
If you are buying around Blue Springs, Lee’s Summit, Grain Valley, or the surrounding eastern Kansas City communities, visit my buyer services page or contact me. You do not need to have every answer before starting the conversation.
About the author
Jennifer Case, REALTOR®, is the owner of Jen Case Homes and an agent with Premium Realty Group. She helps buyers and sellers in Blue Springs, Lee’s Summit, Grain Valley, and surrounding eastern Kansas City communities, including acreage and rural homes.