An inspection and an appraisal can both involve someone visiting the house after your offer is accepted. Both can generate a report. And both can affect what happens next. No wonder buyers mix them up.
They answer different questions: the inspection helps you understand the home’s condition; the appraisal provides an opinion of its value. One does not replace the other.
The difference at a glance
Question | Home inspection | Home appraisal |
|---|---|---|
Main purpose | Evaluate accessible systems and identify condition concerns. | Develop an independent opinion of property value. |
Usually arranged by | The buyer, working within contract deadlines. | The mortgage lender when an appraisal is needed. |
What you receive | A report of observations, limitations, and recommended follow-up. | A valuation report describing the property and supporting the value conclusion. |
What it does not promise | A perfect house or trouble-free future. | That every system works or that the home will resell for a particular amount. |
The inspection: what am I buying?
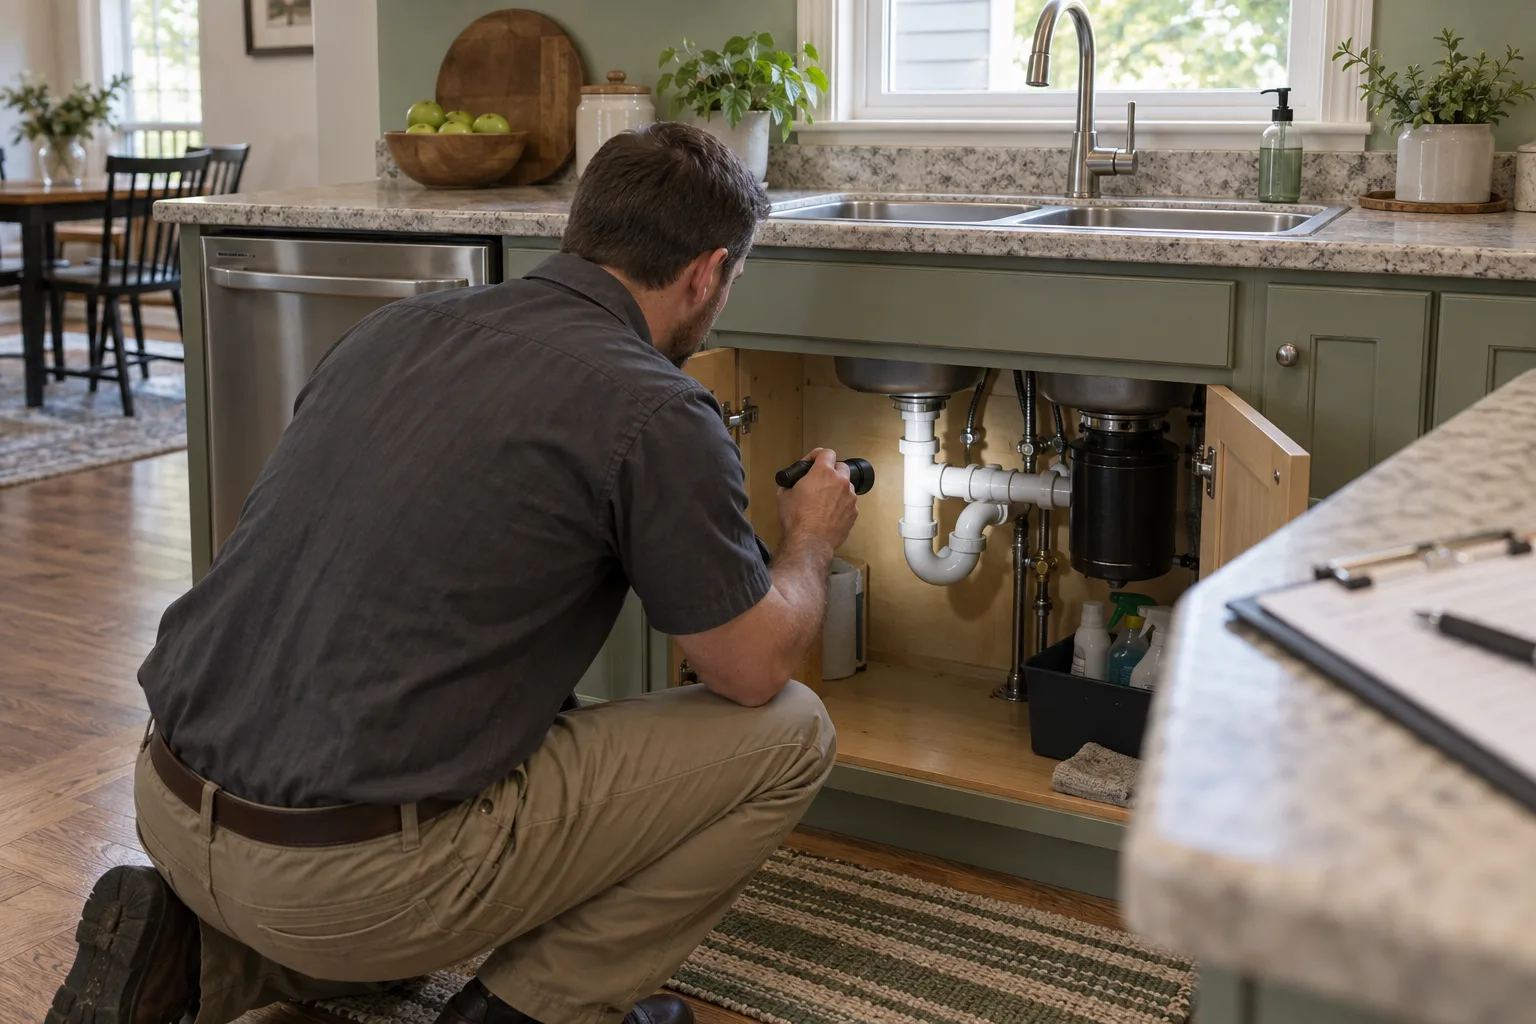
At a showing, you might be thinking about furniture, sunlight, or whether the yard works for your dogs. A home inspector is looking at the property with a different checklist.
The findings help you ask practical questions. Is that stain evidence of an active leak? Does the electrical concern need an electrician? Is a system working today but worth budgeting to replace later?
I would not use the report’s page count to judge the house. I would use the findings to decide what needs clarification. For inspection-day details, rural-property considerations, and handling the report, read What Is a Home Inspection in Missouri? What Buyers Should Expect.
The appraisal: does the value support the transaction?
An appraiser considers the property and relevant market evidence to form an independent opinion of value. In a financed purchase, the lender uses valuation information as part of the lending decision. Some eligible loans use an alternative to a traditional appraisal; ask your lender what your transaction requires.
The CFPB’s appraisal explanation is a useful starting point. Receiving a value at or above the agreed price does not mean you can skip learning about the house’s condition.
Can one report be fine while the other raises concerns?
Yes. Imagine a home where the inspection reveals a plumbing leak, but the appraised value supports the purchase price. The value result does not make the leak disappear. You still need to understand the repair and your contract options.
Now imagine a well-maintained home with few inspection concerns but an appraisal below the agreed price. Its condition and the financing numbers are separate conversations. Neither scenario automatically tells you to buy or walk away.
Some loan programs also have property-condition requirements. Ask your lender whether an appraisal condition or required repair affects approval. Those requirements do not turn the appraisal into a comprehensive inspection.
Which happens first, and who pays?
There is no sequence I would promise for every purchase. We need to coordinate your inspection deadlines with your lender’s appraisal and underwriting timeline. Ask when each service must be ordered, when payment is due, and what happens if the transaction does not close.
Buyers commonly pay separate charges for these services. For your actual budget, get quotes and review the lender’s disclosures rather than relying on a national average. My Missouri closing-cost guide puts those expenses into the larger picture.
Two questions to keep on your list
Before proceeding, I want you to be able to answer: “Do I understand the condition concerns?” and “Do I understand the financing and cash needed?” If either answer is no, let’s identify who can give you the missing information.
Buying in Blue Springs, Lee’s Summit, Grain Valley, or the surrounding eastern Kansas City area? Visit my buyer services page or reach out. I can help keep these moving parts organized without expecting you to become an inspector or an appraiser.
About the author
Jennifer Case, REALTOR®, is the owner of Jen Case Homes and an agent with Premium Realty Group. She helps buyers and sellers in Blue Springs, Lee’s Summit, Grain Valley, and surrounding eastern Kansas City communities, including acreage and rural homes.